Vaud
What Vaud’s tax-cut vote means for residents and cantonal competition
Vaud voters have approved a 12% reduction in income and wealth taxes, although the canton will remain above the Swiss average tax burden. The article will examine who benefits, how the measure affects cantonal finances and whether it could intensify tax competition between cantons.
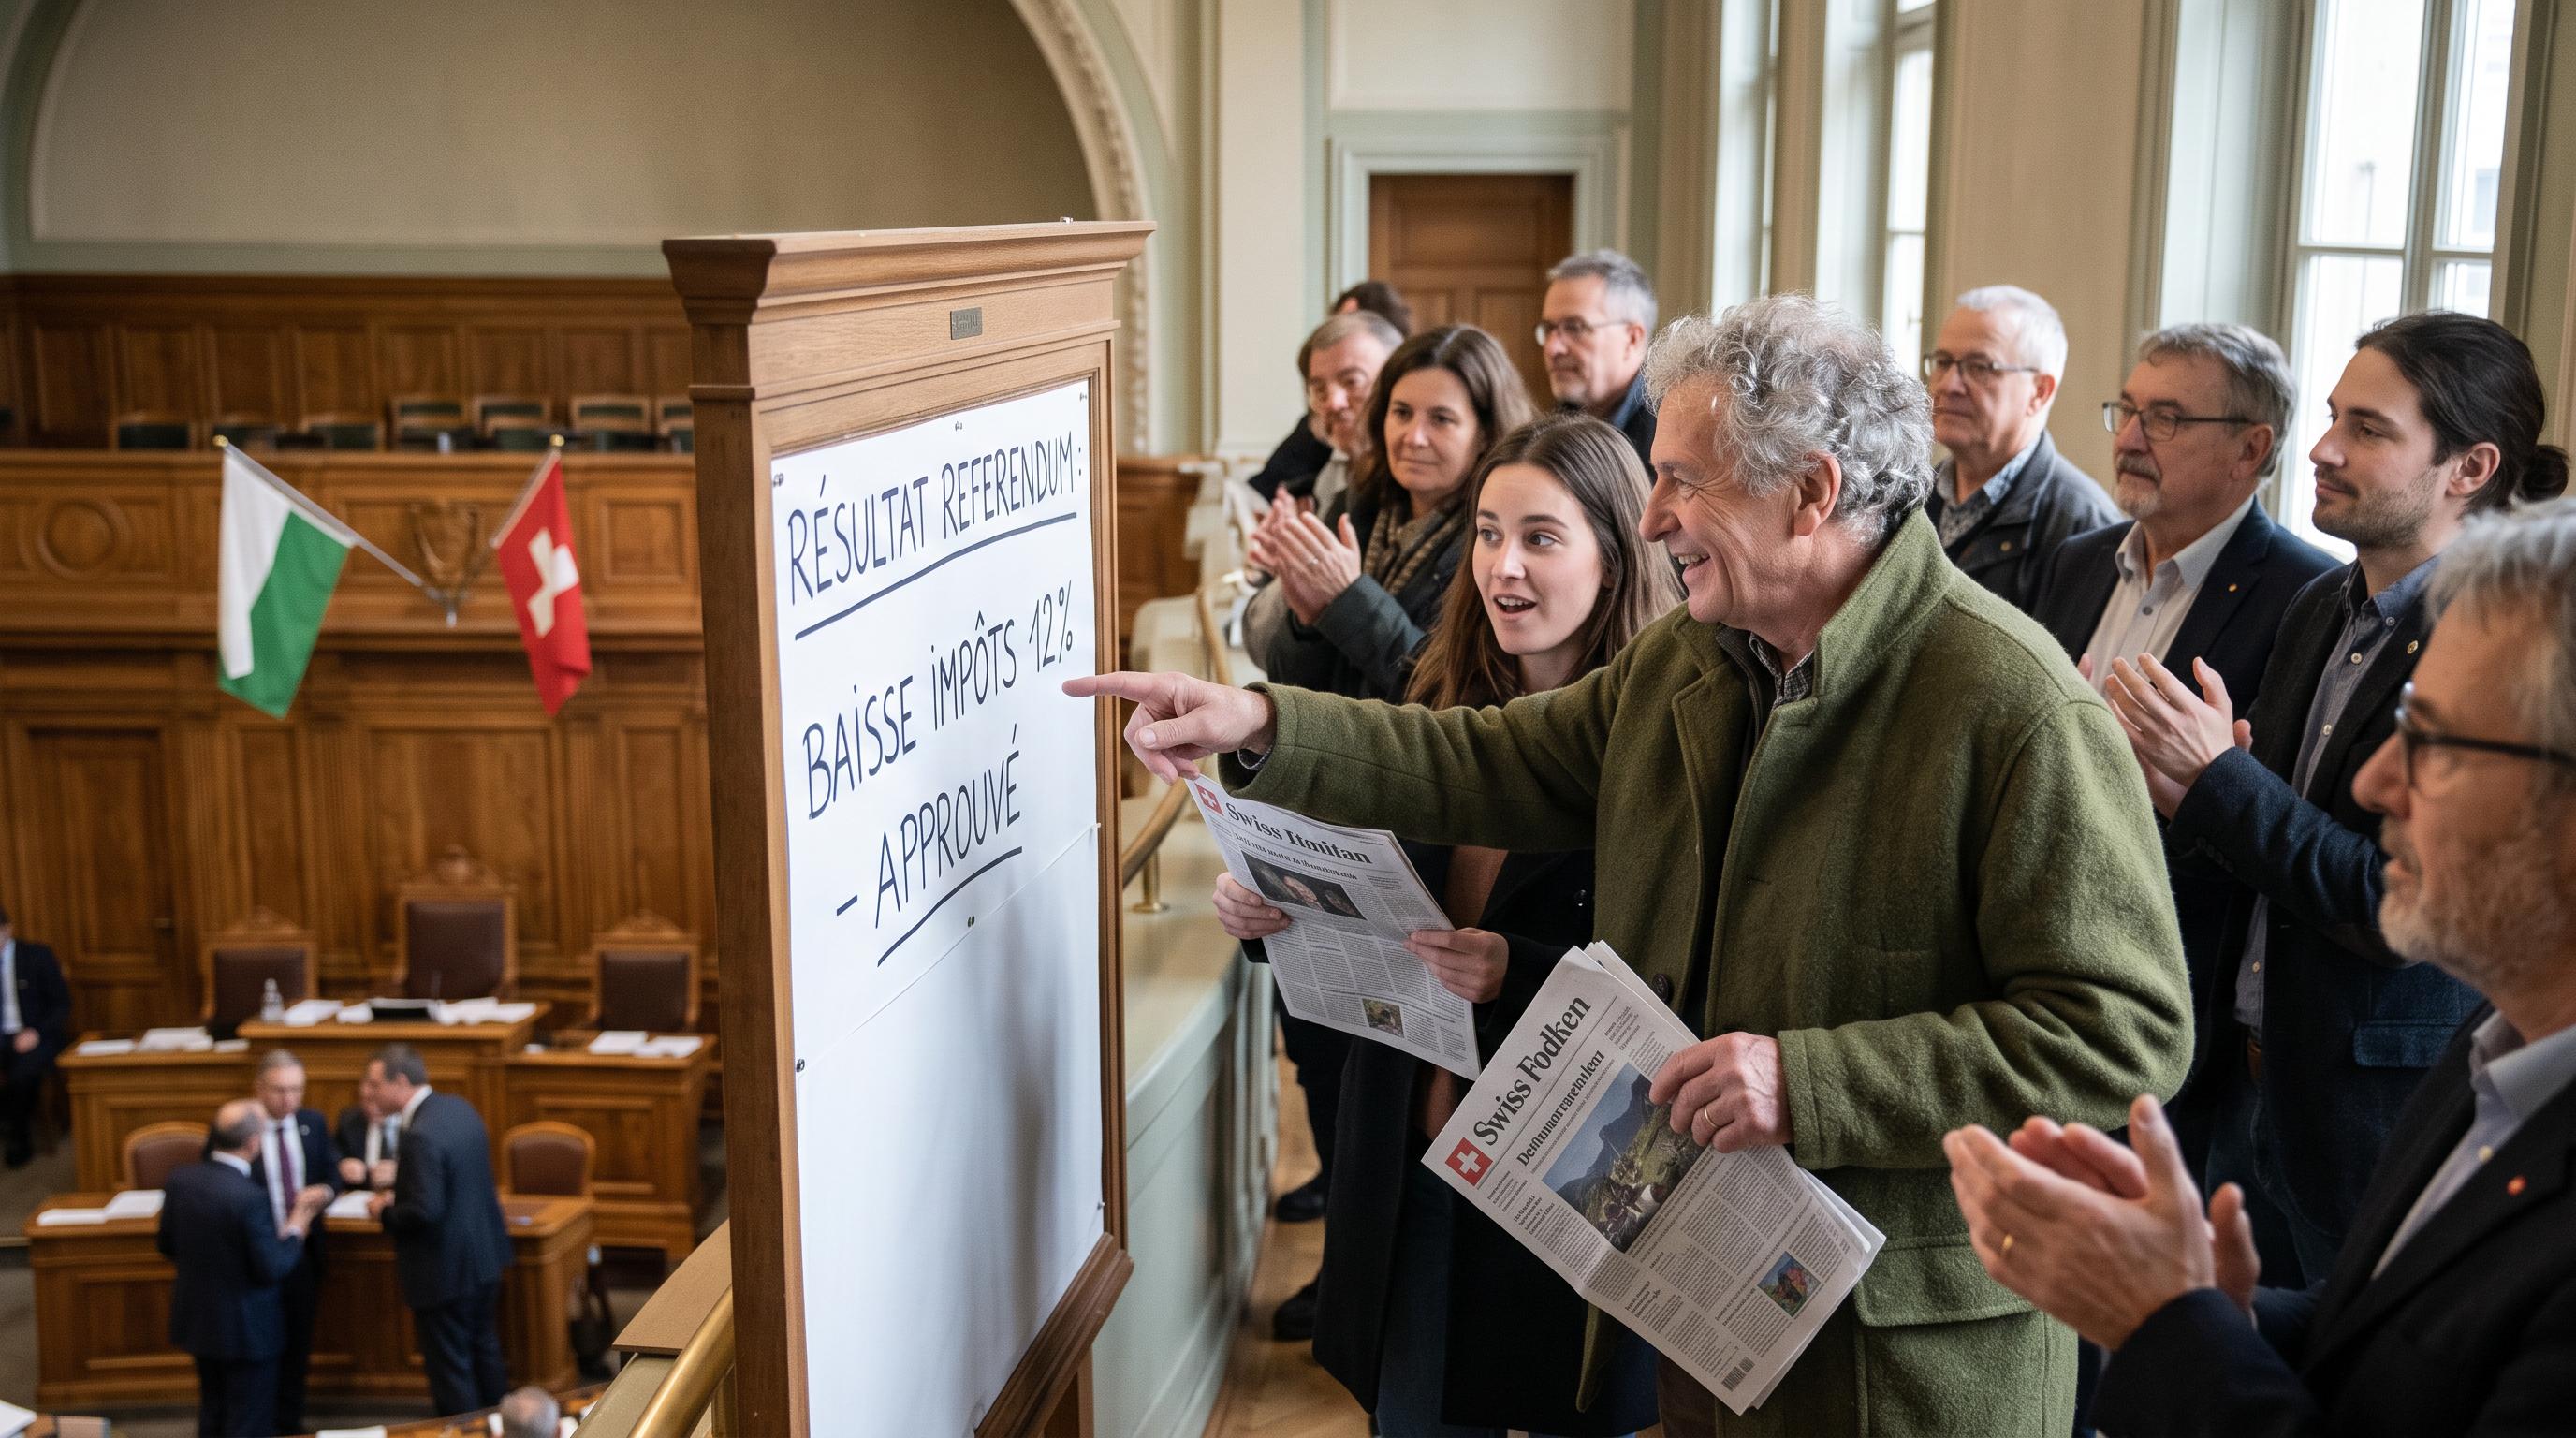
Vaud Voters Cut Taxes, Not the Canton’s Identity
53.1% of Vaud voters backed a 12% cut in income and wealth taxes, giving the canton’s taxpayers relief while leaving Vaud firmly in Switzerland’s high-tax group. The measure will take effect from 2027, according to the source material, and will be felt most clearly by residents with taxable income or wealth exposed to the affected rates.
The vote matters because Vaud has long financed a broad public sector through progressive personal taxation. The canton funds substantial spending on health, welfare, education and infrastructure. That model has helped make Vaud an attractive place to live and work, while also placing it near the top of national tax tables.
Residents should therefore expect a reduction in their bills, not a wholesale change in the canton’s fiscal identity. Middle and upper-middle income households, along with better-off taxpayers, will continue to face a heavier burden than many comparable households elsewhere in Switzerland. Vaud is likely to remain close to Geneva and Basel-City among the country’s most highly taxed cantons.
The political message from voters is precise: lower the burden, while retaining the services and redistribution associated with Vaud’s existing model.
Track Who Gains From the New Rates
The 12% reduction will not affect every household equally. Its practical value will depend on taxable income, taxable wealth and the canton’s progressive rate structure. Residents with larger tax bases stand to see the biggest franc savings, while lower-income households may receive more limited gains in absolute terms.
That distribution reflects the structure of Vaud’s tax system. The canton ranks particularly high for middle and upper-middle income taxpayers, as well as for better-off residents. Even after the reform, taxpayers with more than CHF 100,000 in taxable income or wealth are likely to find Vaud near the top of the national ranking.
The reform also arrives as Switzerland prepares to move toward individual taxation for married couples. Swiss voters approved that change in March 2026, and cantons must apply it by January 1, 2032. Vaud will need to redesign its tax brackets and related rules before that deadline. The work could alter how the 2027 reduction is distributed between households and taxpayers.
For residents, the headline percentage is only the first measure. The decisive figure will be the final bill after deductions, household circumstances and the coming federal reform are taken into account.
Make the Budget Case Before 2027
Vaud’s finances are already under pressure, making the timing of the vote as important as the size of the reduction. A 12% cut in income and wealth taxes reduces revenue from the canton’s core personal tax base. The eventual fiscal effect will depend on taxpayer behaviour, economic growth and whether lower rates attract or retain residents with high incomes and substantial wealth.
The source material does not provide a cost estimate for the measure, so the budgetary impact cannot be stated precisely. It does establish that the canton’s finances are under growing strain. That pressure will force the next government to weigh tax relief against spending on public services and transfers.
The immediate political pause may be short. Business groups and the political right are not preparing another push for personal tax cuts at present. Their focus has shifted to the tax brackets introduced in 1987, which will need revision as Switzerland adopts individual taxation for married couples.
The next major test is likely to come after Vaud’s cantonal elections in summer 2027. By then, residents and lawmakers will have more evidence about revenue, household savings and the government’s capacity to maintain services. The tax debate will return with those figures at its centre.
Watch the Cantons Move in Formation
Western Switzerland is moving through a wider cycle of tax reform. Geneva introduced an average 8% income-tax cut in 2025, yet its worsening fiscal position has reopened discussion about every option, including tax increases. Finance Minister Nathalie Fontanet has said that no option is off the table.
Valais has offered tax relief to taxpayers its parliament defines as middle class since last year and has expanded household deductions. Bern is preparing a tax-law revision that could reduce bills for some low and middle-income earners by as much as 20% from 2027, phased in over time. In Neuchâtel, members of the Swiss People’s Party, Liberals and Centre submitted an initiative in July 2025 calling for a 10% cut by 2030.
These measures are not identical. They target different taxpayers, use different timetables and remain at different stages of approval. Their common direction is clear, however. French-speaking cantons, where tax burdens often exceed those in German-speaking Switzerland, are under pressure to make the cost of living and working more competitive.
Vaud’s vote adds weight to that regional movement. It also gives neighbouring cantons another benchmark when they assess the balance between revenue, services and location decisions.
Prepare for the Next Cantonal Contest
Vaud will remain a high-tax canton after the vote, but its neighbours will be watching the result closely. Cantonal competition rarely turns on one percentage point alone. Companies and households compare tax rates alongside schools, transport, healthcare, housing, labour markets and the reliability of public administration.
Vaud’s established model gives it strong public services and a substantial redistribution system. Those commitments help explain why the canton has historically accepted higher personal taxes than much of German-speaking Switzerland. The approved reduction changes the balance at the margin. It may make Vaud more competitive for some taxpayers without forcing a wholesale retreat from its public-service model.
The harder decisions will come when revenues and spending collide. Geneva’s experience shows that a tax cut can coexist with renewed pressure for higher revenue. Vaud will also have to coordinate its 2027 reform with the federal move toward individual taxation, due by January 1, 2032.
For Swiss taxpayers, the result is a more active cantonal marketplace. For Vaud’s government, the task is to show that a lower rate can coexist with credible finances. The next election will provide the first major verdict on whether voters believe that promise.